At EuroFinance 2026 in Barcelona, we sat down with Domenico De Maio from Helsinn Group for a conversation about, amongst other topics, the differences between the treasury function in mid-cap and large-cap environments.
Domenico has spent around 15 years with Helsinn, giving him a long-term perspective on how treasury develops alongside a business and how the priorities of a treasury function are shaped by the organisation it serves.
This discussion inspired us to explore this topic further. In particular, it raised an interesting question around how we think about treasury maturity and whether the practices of large multinational organisations should really be used as the benchmark for mid-sized companies.
The following is my take on that question.
Mid-cap treasury cannot simply be treated as a smaller version of large-cap treasury.
It sounds straightforward, but it challenges an assumption that appears quite often when companies discuss treasury maturity. There can be a tendency to see treasury development as a single journey towards the same destination: more automation, more systems, greater centralisation, increasingly sophisticated forecasting and more advanced liquidity structures.
In other words, look at what the largest multinational companies are doing and reproduce it on a smaller scale.
In practice, however, the right treasury model depends far more on the organisation itself.
Different organisations require different treasury models
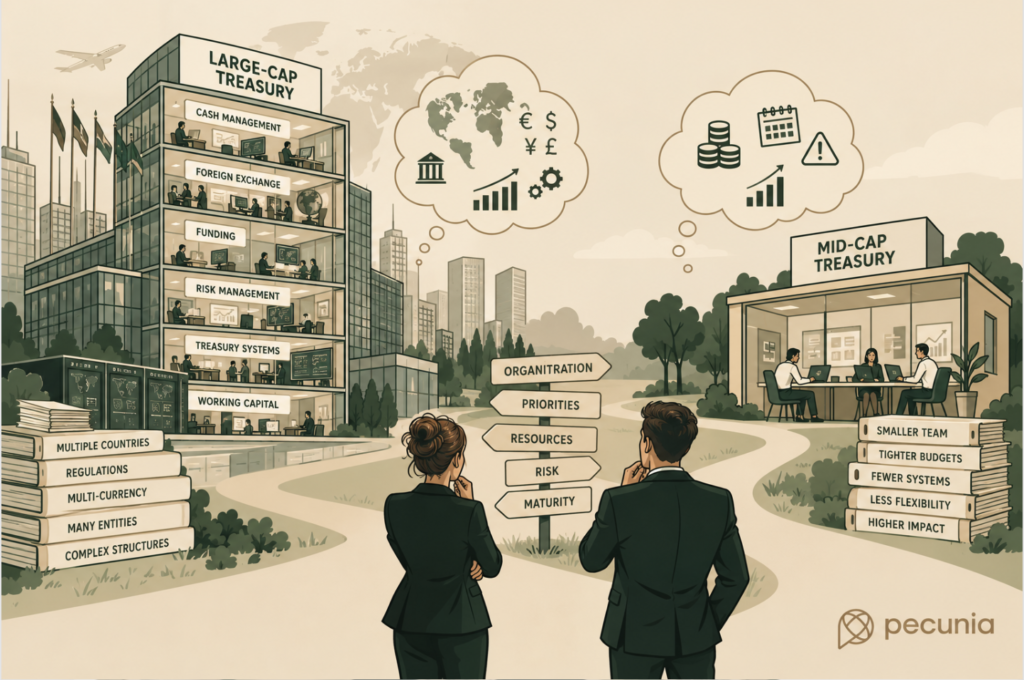
A large multinational might have dedicated specialists responsible for cash management, foreign exchange, funding, treasury systems, financial risk and working capital. A mid-sized business may have two or three people covering all of those areas.
In some cases, it may be one person.
That difference in resources fundamentally changes how treasury operates and, importantly, how priorities need to be set.
Mid-cap treasury functions often work with smaller teams, tighter budgets, fewer technological resources and more limited access to external funding. There may also be significantly less room for error.
For a multinational with billions of euros in available liquidity, a forecasting deviation can be inconvenient. For a mid-sized company operating with limited headroom under its financing facilities, the same forecasting deviation can quickly become a matter requiring the CFO’s attention.
This means liquidity management becomes extremely practical.
The key questions are not necessarily about designing the theoretically most sophisticated treasury structure. They are often much more immediate:
Where is our cash today? When will we need it? How much liquidity headroom do we genuinely have? What could surprise us over the next 13 weeks?
These questions may appear simpler than the challenges faced by a multinational treasury department, but that does not make them less demanding. In many cases, having fewer resources and less margin for error makes strong treasury discipline even more important.
Working capital starts with understanding the problem
Working capital is a good example of where this difference becomes visible.
When companies decide that working capital needs improvement, the conversation can quickly move towards technology: forecasting platforms, analytics tools, artificial intelligence, supply-chain-finance solutions or process automation.
All of these can play an important role.
But technology cannot compensate for poor cash discipline.
The starting point is often much more basic: measure what is happening and understand where cash is getting stuck.
Why are customers paying later than expected? Why are invoices being issued late? Why are agreed payment terms regularly overridden? Why is inventory sitting unused? Why are suppliers being paid earlier than necessary?
Once those questions have been answered, the next challenge is creating awareness and, ultimately, ownership.
This is where working capital becomes much more than a treasury topic.
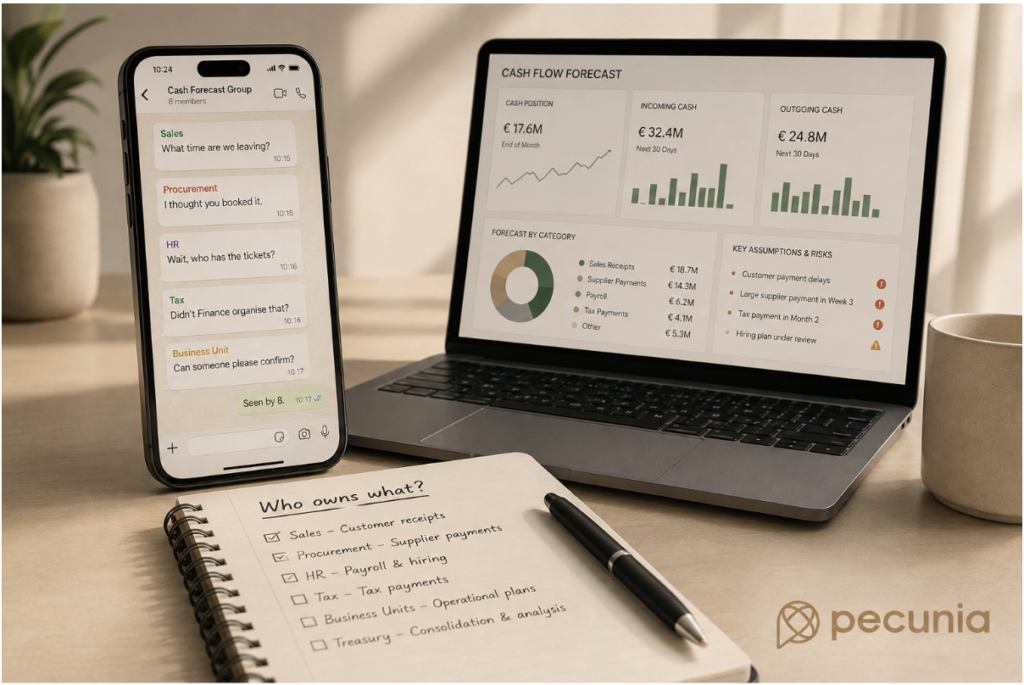
Treasury sees the liquidity impact, but the decisions that create that impact are spread across the organisation. Sales manages customer relationships and negotiates commercial terms. Procurement negotiates with suppliers. Accounts receivable manages collections. Accounts payable controls payment execution. Operations influences inventory levels.
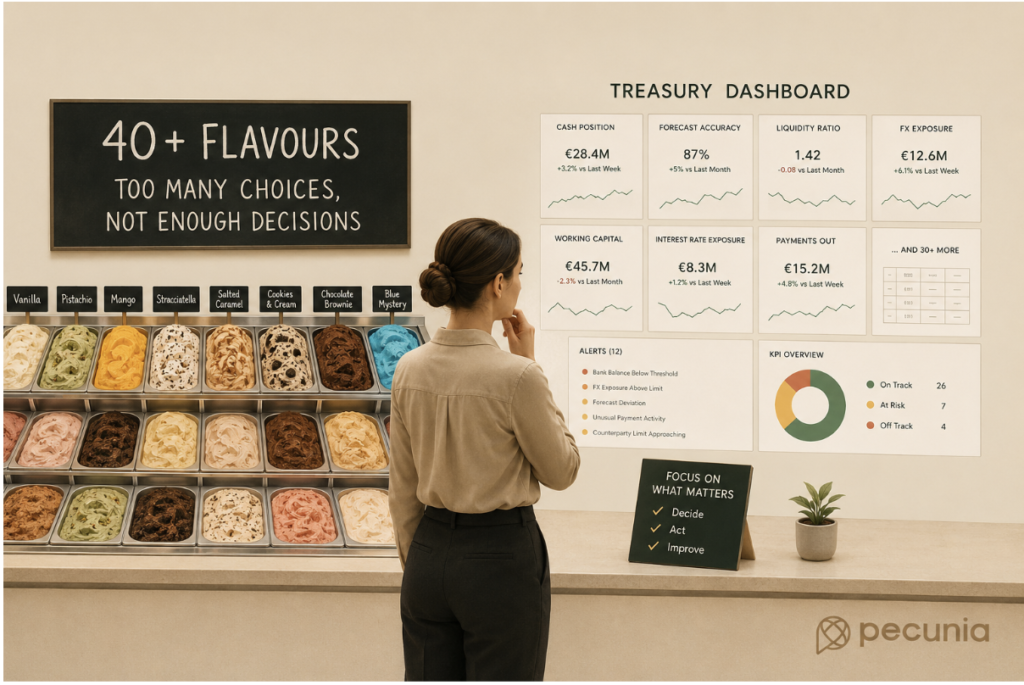
The cash may ultimately appear on the treasury dashboard, but the actions that determine where that cash goes happen throughout the business.
Treasury has to make the organisation think about cash
For me, this is one of the most interesting parts of the treasury function.
Treasury is not only responsible for managing liquidity. It also has to help the wider organisation understand how its decisions affect liquidity.
A salesperson may celebrate closing a €5 million contract. Treasury will want to know when the company will actually receive the cash.
Procurement may successfully negotiate a 3% discount from a supplier. Treasury may ask what happened to the payment terms in exchange.
Operations may want an additional €10 million of inventory available as a buffer. Treasury will look at how long that cash is likely to remain tied up.
None of these functions are necessarily making the wrong decision. They are simply working towards different objectives and are measured against different KPIs.
That is why improving working capital is rarely achieved through a treasury initiative alone. A company can implement sophisticated dashboards and generate excellent cash-flow analysis, but if the wider organisation does not feel responsible for cash, sustainable improvement will remain difficult.
The challenge is therefore cultural as much as technical.
Complexity versus constraint
So which environment is more difficult: large-cap or mid-cap treasury?
There is no simple answer.
Large organisations have enormous complexity. Treasury teams may have to deal with multiple countries, currencies, banks, regulations, systems, legal entities and internal stakeholders.
Mid-cap organisations face a different challenge: constraint.
They typically operate with fewer people, less funding flexibility, fewer systems, less internal redundancy and, in many cases, far less room for mistakes.
The skills required can therefore be quite different.
A highly effective mid-cap treasurer may need to move constantly between strategic questions and operational execution. One moment may involve discussing financing capacity with the CFO; the next may involve resolving a banking issue, reviewing a 13-week forecast or chasing overdue information from another department.
That breadth is not a sign that the treasury function is less mature. It is simply the reality of operating in a different organisational environment.
Treasury maturity should be relative to the business
Perhaps, then, we should be more careful about how we define treasury sophistication.
The goal should not necessarily be to make every treasury department resemble the treasury function of a large multinational.
A better question is:
Does treasury have the right setup for the company it actually serves?
For many mid-cap companies, excellent treasury may not mean implementing the most sophisticated technology or building the most complex liquidity structures.
It may mean having strong visibility over cash, understanding where liquidity is going, creating discipline around working capital and ensuring that the wider organisation understands the financial consequences of its decisions.
Revenue matters. Profit matters.
But ultimately, someone still has to collect the cash.
And, as simple as that sounds, getting an entire organisation to think that way remains one of treasury’s most important challenges.
Is your treasury setup still fit for the business it serves?
Treasury maturity is not about copying what the largest organisations are doing. It is about building the right processes, systems and capabilities for your organisation’s size, complexity and ambitions.
At Pecunia, we support treasury teams in strengthening liquidity management, working capital, forecasting and treasury operations, with solutions tailored to the realities of the business.
Want to explore where your treasury function could improve? Contact us.